Cyberattacks on African organisations increased by more than 421 per cent between 2016 and 2025, exceeding the 307 per cent growth recorded globally, according to a white paper by Mastercard.
The report, titled: Africa’s Digital Defence Race, said Mastercard Cyber Insights recorded 69,236 cyber events targeting African organisations in 2025, equivalent to approximately one event every eight minutes.
It identified technology, the public sector and financial services as the three most targeted sectors, accounting for 44 per cent of observed cyber activity. Personal information, financial information and customer-facing services accounted for 27 per cent of targeted assets.
The report warned that Africa’s expanding digital economy was exposing businesses, consumers and financial systems to growing cybersecurity threats, while gaps in digital infrastructure, skilled personnel and regulatory coordination threatened to undermine the continent’s digital transformation.
The white paper called for increased investment in cybersecurity capabilities, stronger regional cooperation and regulations tailored to Africa’s evolving digital landscape.
It noted that Africa processed $1.4 trillion in mobile money transactions in 2025, representing approximately two-thirds of global mobile money transaction value.
However, the rapid expansion of digital transactions has also attracted cybercriminals seeking to exploit vulnerabilities in financial platforms, business networks and interconnected systems.
The report identified shortages of cybersecurity professionals, infrastructure deficiencies, regulatory challenges and inadequate cooperation among African countries as major obstacles to building a resilient digital ecosystem.
It particularly highlighted the vulnerability of small and medium-sized enterprises (SMEs), which account for more than 90 per cent of private businesses across Africa and increasingly depend on digital systems to operate.
According to the white paper, a serious cyberattack could threaten the survival of a small business, while disruptions to interconnected digital platforms could affect supply chains, increase operating costs, erode consumer confidence and weaken economic growth.
It also observed that Africa’s cyber insurance market remained relatively underdeveloped, limiting the financial protection available to businesses against cyber-related losses.
The report argued that stronger cybersecurity was essential to encouraging digital adoption among small businesses and protecting the wider economy from the consequences of cybercrime.
On regulation, Mastercard noted that although several African countries had introduced data protection frameworks modelled on the European Union’s General Data Protection Regulation, the continent’s distinct economic and technological realities required more tailored approaches.
Mobile money transactions and cross-border informal trade conducted through financial technology platforms were among the activities that might not fit neatly into conventional regulatory categories, the report stated.
It recommended risk-based and technology-neutral regulations that encourage innovation, facilitate trusted cross-border data transfers and protect consumers while strengthening digital security.
The white paper also emphasised regional cooperation, noting that cybercriminals frequently operate across national borders, making isolated enforcement efforts less effective in dismantling criminal networks.
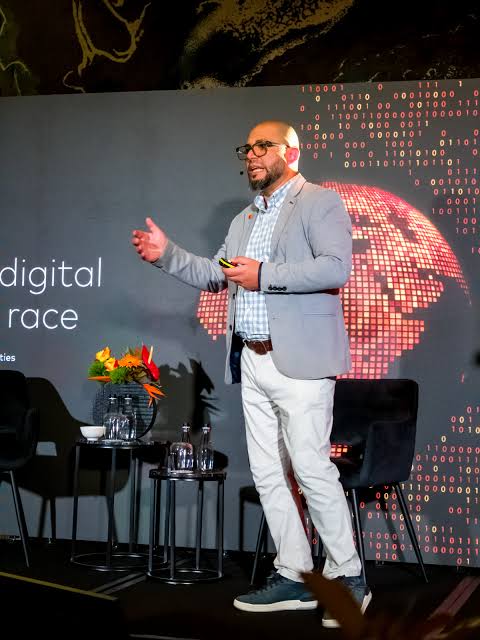
Presenting the report, Mastercard’s Senior Vice President and Customer Solutions Center Lead for Africa, Shabir Ahmed, said the continent’s digital growth had created significant opportunities for businesses and individuals, making cybersecurity a leadership priority.
“Africa’s digital growth is creating real opportunity for people and businesses across the continent, and protecting it has become a leadership priority. As threats become more sophisticated and coordinated, our response has to be just as coordinated,” Ahmed said.
He said Mastercard had launched the Africa Cybersecurity Center of Excellence to bring public- and private-sector stakeholders together to share intelligence, knowledge and best practices.
“Building that resilience together is how Africa continues to grow with confidence,” he added.
The report also highlighted differences in cybersecurity risks across African markets. It noted that Nigeria, which hosts one of the continent’s largest fintech ecosystems, accounted for a significant share of observed cyberattacks in Africa in 2025.
South Africa’s concentrated financial sector was the target of 12.6 per cent of the continent’s observed attacks, according to the white paper.
We’ve got the edge. Get real-time reports, breaking scoops, and exclusive angles delivered straight to your phone. Don’t settle for stale news. Join LEADERSHIP NEWS on WhatsApp for 24/7 updates →
Join Our WhatsApp Channel