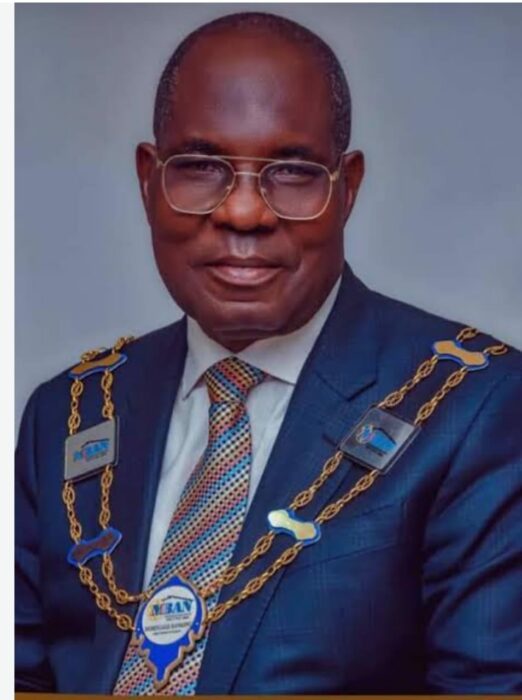
A former President of the Mortgage Banking Association of Nigeria (MBAN), Mr Ebilate Mac-Yoroki, has said Nigeria can achieve an annual housing delivery target of 500,000 units by leveraging the capital market to mobilise long-term institutional funding.
Mac-Yoroki, who is also Chairman of CityCode Mortgage Bank Limited, made the proposal on Friday evening at the MBAN Annual Conference and Gala Dinner in Abuja.
He identified capital mismatch and information asymmetry as major structural challenges limiting housing development in the country, arguing that achieving the housing target would require a shift from traditional budgetary allocations to a market-driven financing framework.
According to him, Nigeria has a housing deficit exceeding 17 million units, while public and private housing delivery mechanisms have historically produced fewer than 50,000 formal units annually.
“Achieving a target of 500,000 housing units per annum requires solving the primary systemic failures in Nigerian real estate: capital mismatch and information asymmetry,” he said.
Mac-Yoroki explained that one of the major challenges confronting housing finance was the mismatch between the short-term deposits held by commercial banks and the long-term funding requirements of mortgages, which typically run for 15 to 25 years.
He noted that commercial banks’ reliance on short-term retail deposits, typically between 30 and 90 days, made them structurally unsuitable for financing long-term mortgages at affordable interest rates.
“Targeting 500,000 units requires institutional patient capital to bridge this duration gap,” he stated.
He proposed mobilising funds from pension fund administrators (PFAs), insurance asset managers and foreign portfolio investors to provide long-term financing for mortgage lending and large-scale housing development.
The former MBAN president also advocated the expansion of mortgage-backed securities, covered bonds and residential real estate investment trusts (REITs) to enable mortgage banks to access institutional funding and recycle liquidity into new housing loans.
He said residential REITs and forward-purchase off-take funds could channel long-term capital from pension assets into large-scale housing projects while providing developers with guaranteed exit channels before construction begins.
This, he argued, would reduce the risk of unsold properties and provide developers with greater certainty in financing new projects.
Mac-Yoroki further recommended blended financing arrangements, including green and social housing bonds, as well as government-backed infrastructure bonds, to lower borrowing costs and improve mortgage affordability.
On property administration, he proposed the establishment of a Central Housing Depository (CHD), a digital infrastructure for consolidating property ownership rights, mortgages and encumbrances.
He said the proposed system would address the challenges associated with Nigeria’s paper-based and decentralised land registration processes.
According to him, the Central Housing Depository would facilitate digital property titling, accelerate title transfers, improve verification of ownership and reduce multiple-sale fraud.
He noted that more than 90 per cent of land in Nigeria remained unregistered, describing the situation as a major obstacle to transforming real estate into a transparent and investable asset class.
The paper also proposed that the MBAN Secretariat serve as the primary clearinghouse and repository for national housing data, tracking mortgage originations, disbursements and loan performance across public interventions, institutional funding pools and commercial mortgage banks.
Mac-Yoroki urged the Federal Ministry of Housing and Urban Development to establish an Inter-Agency Housing Data Directorate to work with MBAN in ensuring that government policies, land reforms and budgetary allocations were guided by reliable market information.
He said improved data collection would support credit assessment, enable automated property valuation and help developers identify locations with genuine demand for affordable and mid-income housing.
On supply-side challenges, he identified land acquisition difficulties, construction cost volatility, inadequate infrastructure and high mortgage interest rates as major constraints to expanding housing delivery.
He called for the harmonisation of Governor’s Consent procedures under the Land Use Act, adoption of digital Geographic Information Systems across states and increased local production of building materials to reduce dependence on imported construction inputs.
He also recommended public-private partnerships to finance roads, electricity and water infrastructure around housing developments, noting that off-site infrastructure could account for between 20 and 30 per cent of total housing development costs.
To improve access to homeownership, Mac-Yoroki proposed single-digit interest rate subsidies and shared-equity schemes to enable low- and middle-income earners to service long-term mortgages despite prevailing inflationary and interest-rate pressures.
He outlined a 36-month implementation roadmap, beginning with the development of regulatory guidelines for the Central Housing Depository in collaboration with the Securities and Exchange Commission, Central Bank of Nigeria and Federal Ministry of Housing and Urban Development.
The second phase would involve launching securitised residential mortgage-backed securities through Nigeria Mortgage Refinance Company liquidity frameworks and integrating state Geographic Information Systems into the proposed depository.
The final phase would focus on deploying forward-purchase REIT capital to finance large-scale residential developments and launching national Automated Valuation Models.
Mac-Yoroki maintained that the combination of capital market financing, digital property administration, reliable housing data and targeted policy reforms would provide a sustainable pathway to expanding housing supply.
“Deepening capital markets creates the funding capacity, while a Central Housing Depository and standardized housing data provide the transparency, velocity, and trust required to attract institutional capital at scale,” he said.
We’ve got the edge. Get real-time reports, breaking scoops, and exclusive angles delivered straight to your phone. Don’t settle for stale news. Join LEADERSHIP NEWS on WhatsApp for 24/7 updates →
Join Our WhatsApp Channel