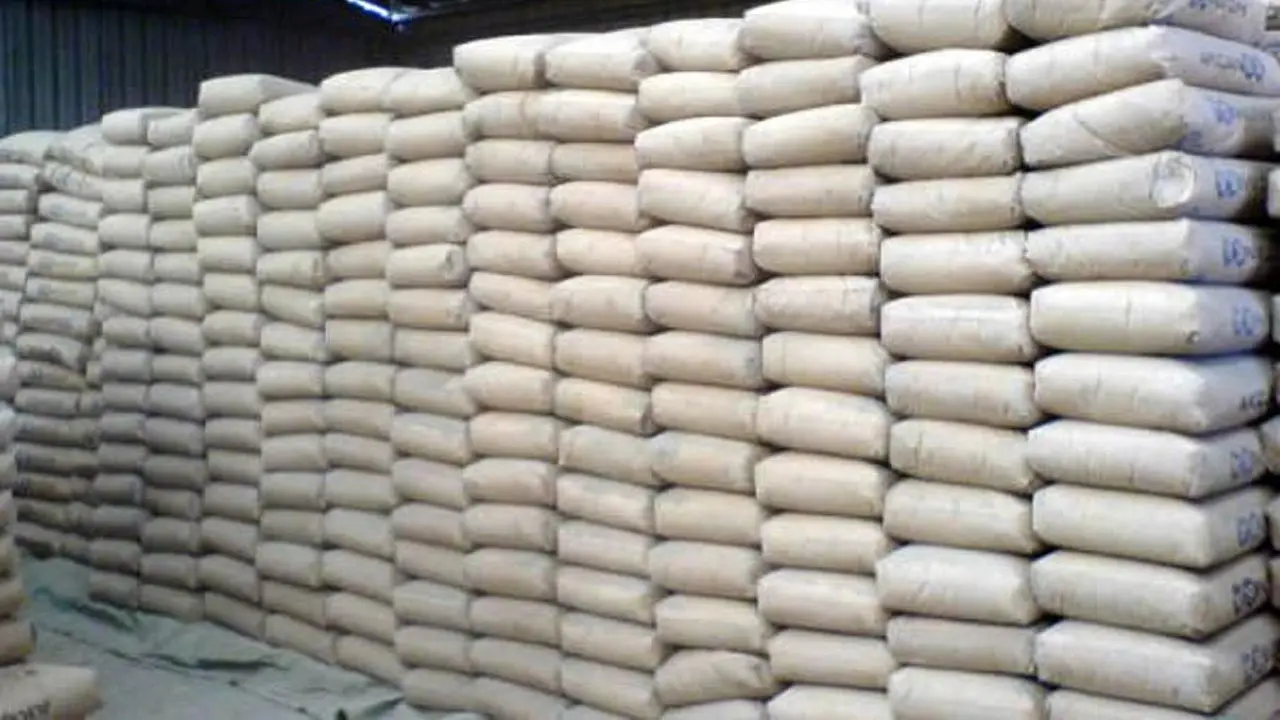
Dangote Cement Plc, BUA Cement Plc and HBM Nigeria Plc have posted a combined revenue of N5.79 trillion in the nine months to September 30, 2026, highlighting the sector’s strong earnings performance amid persistent concerns over rising building costs and declining housing affordability.
The combined figure increased by 20.8 per cent from N4.79 trillion recorded in the corresponding period of 2025, was driven by sustained price hikes, with retail cement now selling above N12,500 per bag in Lagos and other major cities, even as production costs grew slower than sales.
The breakdown shows Dangote Cement earned N3.774 trillion, up 19.6 per cent, with profit after tax of N974.8 billion, up 31.2 per cent, as revenue growth was supported by improved performance in its Nigerian and Pan-African operations.
Its Nigerian business generated N2.67 trillion in revenue, compared with N2.18 trillion in 2025, while its Pan-African operations contributed N1.19 trillion.
BUA Cement grew revenue 26.5 per cent to N1.087 trillion with profit up 60 per cent to N463.1 billion, while HBM Nigeria grew revenue 19 per cent to N928 billion with profit up 31 per cent to N272 billion.
The trio made N1.7 trillion profit after tax in the period, up 38 per cent year-on-year, with operating leverage improving as cost of sales rose only 8.8 per cent at BUA and moderated at Dangote.
A 50kg bag of cement, which sold for approximately N3,300 to N3,500 in 2021, has risen to between N13,000 and N15,000 in several Nigerian markets in 2026.
This represents an increase of more than 300 per cent in five years, placing additional pressure on individuals, contractors and property developers.
It will be recalled that the Federal Competition and Consumer Protection Commission (FCCPC), in its August 2026 preliminary investigation findings, identified possible price manipulation in the cement market.
The commission noted that Nigeria had installed cement production capacity of between 60 million and 65 million metric tonnes annually, against estimated domestic consumption of 25 million to 30 million metric tonnes.
It also observed that the country’s substantial production capacity had not translated into the downward price pressure ordinarily expected in a competitive market.
The commission identified energy expenses, transportation, exchange-rate depreciation and imported machinery and spare parts as some of the factors manufacturers cited for higher cement prices.
Speaking, the chief operating officer, InvestData Consulting Limited, Ambrose Omordion stated that “in any commodity market, producers enjoy pricing power, and that is what we are seeing in Nigeria today. With inflationary pressure and a huge housing deficit, demand for building materials like cement remains inelastic.”
He noted that “cement is one of the most essential materials for construction globally. Where infrastructure deficit is high, demand stays strong, and producers can easily pass costs to consumers.”
He noted that “these companies face high operational costs, capacity expansions, power and funding costs. But because they can increase prices, they sustain strong profitability. That explains the N5.79 trillion revenue in nine months.
“Their ability to generate cash is positive for investors, but if government can provide a friendly environment, especially stable power, it will reduce production costs for essential sectors like housing.”
He added that “currently, cement companies generate their own energy, which adds to cost. Government support in energy and logistics will moderate costs.
“Going forward, with 14.5MT new capacity coming in 2027, supply should improve and market forces will drive prices down. For now, high cement price remains a key driver of high housing cost, because it is a core component of building and infrastructure.”
Also, the chief executive officer of the Centre for the Promotion of Private Enterprise (CPPE), Dr. Muda Yusuf said the N5.79 trillion combined revenue by cement manufacturers does not tell the full story of profitability.
Yusuf, reacting to the nine-month results of Dangote, BUA and Lafarge, said analysis must focus on cost structure and margin trends, saying that “revenue alone does not give the full picture. We need to establish their cost to determine actual profit, and examine profit margin trend over time.”
He cautioned against linking Nigeria’s housing deficit solely to cement price, noting that housing involves multiple inputs, explaining that “housing is not just about cement. Land in Lagos, even on the outskirts, is very expensive. There are electricals, iron rods, roofing sheets, plumbing. We have not established how those other costs have gone up.”
On market structure, he said the sector is competitive, not a monopoly, “we have Dangote, BUA and Lafarge. If concerned about profiteering, we need more competition and the Consumer Protection Council can determine if it is profiteering or rising costs.”
“Cement is bulky and heavy and we lack rail to move it. Production is highly energy-intensive. We must consider these variables before judging their role in housing deficit,” he stated.
We’ve got the edge. Get real-time reports, breaking scoops, and exclusive angles delivered straight to your phone. Don’t settle for stale news. Join LEADERSHIP NEWS on WhatsApp for 24/7 updates →
Join Our WhatsApp Channel