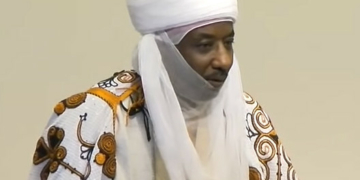
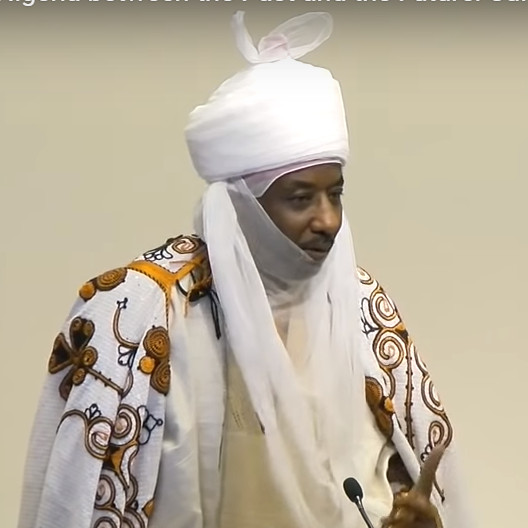
Former Governor of the Central Bank of Nigeria and Emir of Kano, Muhammadu Sanusi II, has admitted that his decision to delay the entry of telecommunications companies into Nigeria’s financial services industry while at the apex bank was a mistake that slowed the country’s financial inclusion drive.
Sanusi, who spoke in Abuja yesterday, at the official launch of the Access to Financial Services in Nigeria 2026 Survey Report in Abuja, said his decision was influenced by concerns over the safety of depositors’ funds following the banking crisis at the time.
The former CBN governor, however, acknowledged that subsequent developments in technology-driven financial services had demonstrated the importance of telcos and technology companies in reaching underserved Nigerians.
Speaking during a fireside chat moderated by the Dean of Lagos Business School, Prof. Olayinka David-West, Sanusi reflected on some of the decisions taken during his tenure between 2009 and 2014.
According to him, the decision was taken shortly after Nigeria had emerged from a banking crisis, when regulators were particularly concerned about protecting depositors.
He said; “I’m responsible for delaying the entry of telcos into this space. Part of the challenge, of course, was we had just come out of a banking crisis where we were worried about depositors’ funds.
“And I wasn’t comfortable allowing companies that I was not a primary regulator of to have access to a huge pool of funds,” he said.
Sanusi, however, admitted that the concern, although well-intentioned, ultimately resulted in what he now considers a wrong policy decision.
“So again, this is one case where you have a good intention, but you take a wrong decision,” he said.
He recalled strongly resisting calls from institutions and other stakeholders to open the financial services space more quickly to telecommunications companies, adding that allowing telcos into the sector earlier could have accelerated Nigeria’s progress in bringing millions of unbanked citizens into the formal financial system.
“I fought the World Bank. I fought everybody. I do think if I had allowed that to happen, it would have been much more progress,” he said.
Sanusi said the expansion of technology-driven financial services in recent years had also exposed the limitations of relying largely on traditional banks to deepen financial inclusion.
His comments came against the backdrop of fresh findings showing that Nigeria has recorded significant gains in financial inclusion, although major gaps remain across income groups, gender and geographical locations.
The 2026 Access to Financial Services survey showed that overall financial inclusion increased to 79 per cent, while financial exclusion declined to 21 per cent from 26 per cent in 2023.
Formal financial inclusion also rose to 73 per cent from 64 per cent in 2023, while the use of digital financial services reached 64 per cent.
Presenting the findings, the Chief Executive Officer of Enhancing Financial Innovation and Access, Foyinsolami Akinjayeju, said pension penetration remained weak despite the broader expansion of financial services.
She said pension coverage stood at about nine per cent nationally, rising to 12 per cent among urban residents and 13 per cent among the richest 60 per cent of the population.
The survey, conducted between April and June 2026 under the supervision of the National Bureau of Statistics, covered 18,679 adults aged 18 and above across the 36 states and the Federal Capital Territory. EFInA said it achieved about 98 per cent of its targeted sample of 18,950 respondents.
The report showed that pension coverage increased to 9.1 per cent of the adult population in 2026 from 7.8 per cent in 2023, leaving roughly nine in every 10 Nigerian adults without any formal pension arrangement.
Speaking, the Director-General of the National Pension Commission, Omolola Oloworaran, said the modest increase highlighted the scale of the retirement security challenge facing the country.
“Pension participation has risen from 7.8 per cent of adults in 2023 to 9.1 per cent in 2026. That progress is real, and it is encouraging. But turn the statistics around. Roughly nine out of every 10 Nigerian adults still stand outside any formal pension arrangement,” she said.
According to Oloworaran, millions of traders, farmers, mechanics, drivers, tailors, hairdressers and workers in the digital economy continue to earn incomes without building adequate financial protection for retirement.
“They work, they earn, they carry this economy. But too many of them are growing older without building any security for the day they can no longer work. That is the great frontier of pension reform,” she added.
She said financial inclusion should go beyond access to bank accounts and extend to products that provide long-term financial security.
Oloworaran said the commission was redesigning pension inclusion through the Personal Pension Plan and called for a dedicated pension inclusion model capable of identifying what would encourage informal-sector workers to save consistently.
She also proposed a pension inclusion map combining EFInA’s survey evidence with PenCom’s regulatory and industry data to identify pension gaps according to geography, gender, age, occupation and income.
According to the report, financial health increased from 16 per cent in 2023 to 25 per cent in 2026, leaving three out of every four adults financially unhealthy.
“Access is increasing, but financial health is not catching up at the same pace,” she said.
The report further identified significant geographical and gender disparities, with formal inclusion standing at 85 per cent among urban adults compared with 58 per cent in rural areas, representing a 27-percentage-point gap.
Formal inclusion among women stood at 67 per cent, with the national gender gap remaining at 11 percentage points.
Reflecting on the broader implications of the findings, Sanusi cautioned against equating access to bank accounts and digital payments with improvements in incomes or economic welfare.
Earlier, the Central Bank of Nigeria (CBN) Governor, Olayemi Cardoso, said the bank has started work on the National Financial Inclusion Strategy (NFIS) 4.0, seeking to ensure that more Nigerians can use financial services safely, affordably and meaningfully.
Represented by the CBN Director, Consumer Protection and Financial Inclusion, Aisha Isa-Olatinwo, Cardoso said the review of NFIS 3.0 had been completed and work had started on the next strategy.
He said; “Within this stability and resilience framework, the CBN is advancing a new generation of inclusion reforms.
“The review of the National Financial Inclusion Strategy (NFIS) 3.0 has been completed, and work has begun on NFIS 4.0, which will raise the way we take financial inclusion to another level,” the CBN said.
Also speaking, Vice-President, Corporate Affairs at Moniepoint Group, Edidiong Uwemakpan, said better use of financial data could help bring excluded Nigerians, particularly women entrepreneurs, into the formal financial system.
She said 62 per cent of female entrepreneurs surveyed in Moniepoint’s impact study received their first formal business loan through the company, while 83 per cent of users reported improved quality of life and 85 per c
ent expressed greater confidence in achieving their financial goals.
We’ve got the edge. Get real-time reports, breaking scoops, and exclusive angles delivered straight to your phone. Don’t settle for stale news. Join LEADERSHIP NEWS on WhatsApp for 24/7 updates →
Join Our WhatsApp Channel