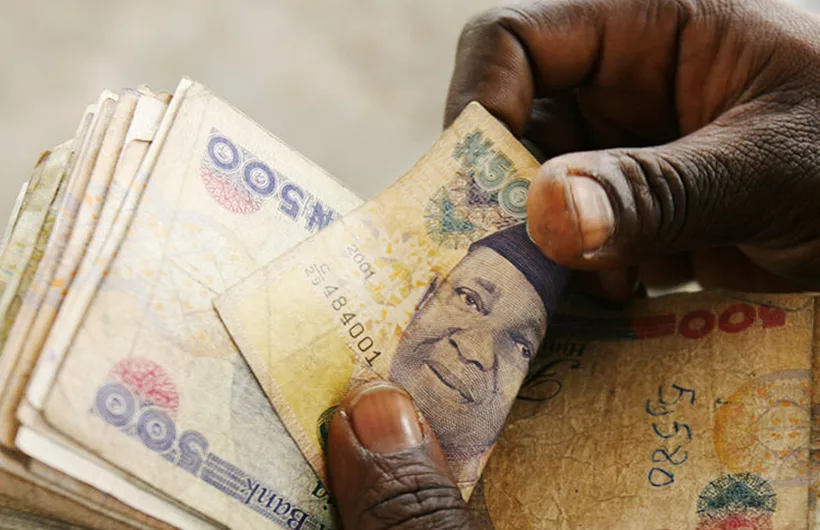
The chairman of the Money Lenders Association, Gbemi Adelekan, has called for stronger credit infrastructure and consumer education to sustain growth in Nigeria’s digital lending market.
Adelekan said that improved credit bureau systems, effective scoring and stronger consumer protection were critical.
He said increasing internet penetration, mobile payments, e-commerce and online banking are changing how Nigerians access financial services, driving demand for quick credit, especially among individuals and small businesses excluded from conventional financing.
He noted that Nigeria’s unbanked population has declined to 21 per cent from 36 per cent in 2020, while broadband penetration has risen above 53 per cent as of January 2026, according to the Nigerian Communications Commission.
Adelekan said digital lending is increasingly complementing traditional banking, with millennials and Gen Z leading the adoption of technology-based financial solutions, alongside freelancers and small businesses, for whom conventional lenders do not require a formal employment history.
“Digital lending leverages online platforms to provide personal and business loans, allowing individuals to access funds quickly and conveniently without the traditional banking processes,” he said.
He, however, warned that loan defaults, inadequate credit information and costly recovery of small-value debts remain major challenges.
He said some borrowers deliberately default, treating digital loans as ‘free money’, affecting lenders’ cash flow and forcing higher interest rates that reduce credit access for low-income Nigerians.
To address this, Adelekan urged government to strengthen credit bureau systems and enforcement of credit reporting to help lenders assess borrowers and identify chronic defaulters.
He also advocated stronger small claims court systems for faster, less costly resolution of small-value debt cases, noting that small-ticket digital loans lack collateral despite high recovery costs.
He called for greater investment in consumer education to improve understanding of loan terms, repayment obligations, and the consequences of default, adding that effective credit scoring would discourage deliberate defaults and enable risk-based pricing.
Adelekan stressed the need for regulation to prevent abusive practices, commending the Federal Competition and Consumer Protection Commission for the Digital, Electronic, Online or Non-Traditional Consumer Lending Regulations, 2025, which promote transparency and responsible lending.
He said fintechs are deploying AI, big data and machine learning to improve credit assessment, manage risks and offer personalised services.
We’ve got the edge. Get real-time reports, breaking scoops, and exclusive angles delivered straight to your phone. Don’t settle for stale news. Join LEADERSHIP NEWS on WhatsApp for 24/7 updates →
Join Our WhatsApp Channel